Home

Thursday, February 16, 2012

VISA payWave can accept smartphone's payment

On January 10, 2012 Visa Inc. and Visa Europe made public their certification of a new range of NFC-capable smartphones that can be used with payWave, the company’s aptly named mobile system for point-of-sale payments. The new phones by Samsung, LG, and RIM have been added to the list of Visa-compliant payment products and can now be commercially deployed by financial institutions.

The specific models include the LG Optimus NET NFC, Samsung Galaxy S II, the Blackberry Bold (9900 and 9790), and the Blackberry Curve (9360 and 9380). On each phone the payWave app is hosted on a secure SIM and makes use of short-range Near Field Communication (NFC) technology to send payment information to contactless terminals. Users literally “wave” their phones at the device.

The potential for smartphones to be used as mobile payment devices is another step forward in moving away from the less-secure magnetic stripe cards that have long dominated the payment sector, and toward chip-enabled cards and other NFC-based payment methods. Not only is the technology more secure, but it allows merchants a broader ability to offer added-value services at the point of sale.

The industry is clearly trending toward NFC-based transactions as the standard, with analysts like Yankee Group predicting the value of these transactions, which stood at $27 million in 2010 will grow to $40 billion by 2014. NFC usage has already gained much broader acceptance in Europe, where Visa has approximately 30 million contactless cards in distribution through 54 banks. By the end of 2012, Visa expects their number of contactless cards to reach 50 billion.
While the chip cards and NFC enabled technologies have been slower to catch on in the United States, Visa has been a leader in offering incentives to merchants to switch out their terminals. All of the smartphones now approved for use with payWave are highly popular with U.S. customers who are rapidly becoming accustomed to using their devices for action-specific purposes well beyond texting and voice calls.

The ease with which such transactions can be handled, mitigating the need to carry multiple cards, is proving highly attractive with the public. Business travelers who routinely use their cards in Europe have been clamoring for American acceptance of the new technologies.
By the end of the 2011 gift-giving season, 50 percent of Americans were carrying some variety of smartphone, with the number expected to grow steadily throughout 2012. As these new users become more comfortable with their devices, and more sophisticated in their use of the available apps like payWave, the transition to NFC technology will gain even more momentum.

GOOD NEWS

Are you tire to find a professional payment gateway for your great business ?
we are the professional online payment gateway ,we can accept visa,master ,JCB,AE credit card payment method ,all high risk  business types welcomed! 99.9 % approval rating!Never locked your merchant account!Low, competitive rates .

skype:goodluck3801
E-mail: paymentgateway@yahoo.cn
website site:http://www.ecpss.com/index_en.html     

Wednesday, February 15, 2012

What transaction processing solution is right for your business?

What transaction processing solution is right for your business? Read through our solutions guide to find which solution your business is going to need and how each solution works. If you have questions about fees, what merchant accounts are, etc., go to our FAQ section. Check out our glossary of terms, also.

Refer to the table below to see which credit card processing solution is right for your business: NR = Not Recommended, POS = Point Of Sale, MOTO = Mail Order/Telephone Order
* In this case, it would be best to have both a swipe terminal and Real-Time solution since running retail (face-to-face) orders through the swipe terminal would incur less charges (lower discount rate and per transaction fee) then it would running the transaction through a Real-Time solution. In short, process your face-to-face orders through the swipe terminal and your MOTO and Internet orders through the Real-Time solution. You’ll need two merchant accounts for this, a retail merchant account and an MOTO/Internet merchant account. Check with a Merchant Account Provider for details as they may be able to cut you a deal.
Now that you know what solutions you can use for your business, take a look at the advantages, disadvantages and detailed explanations so you can effectively determine which solution you want to go with for your business.

Click the graphics below to view detailed information on each credit card processing solution:
Buyers’ Guide to Online Payment Acceptance
Are you new to accepting payment online? We’ve created a guide just for you. It will explain all the details about credit card processing and other payment acceptance solutions you should consider when setting up shop on the Internet. Get the facts before jumping in with both feet. Our easy-to-read guide covers these topics, in detail:
  • Credit Card Acceptance – the basics, rates/fees involved, questions to ask providers, shopping cart software, chargebacks/fraud, SSL certificates and more.
  • Debit/ATM Card Processing & eChecks
  • Micropayments & Digital Cash
  • Escrow Services
Are you ready to take the online payment acceptance journey?
GOOD NEWS

Are you tire to find a professional payment gateway for your great business ?
we are the professional online payment gateway ,we can accept visa,master ,JCB,AE credit card payment method ,all high risk  business types welcomed! 99.9 % approval rating!Never locked your merchant account!Low, competitive rates .

skype:goodluck3801
E-mail: paymentgateway@yahoo.cn
website site:http://www.ecpss.com/index_en.html     

Other Payment Solutions

Have you considered offering your customers other methods of paying for your goods and services? You should! If you’re an Internet merchant you will find that offering more ways to pay can actually increase your sales. People like a varity of ways to order, they like the ability to choose which payment method is most comfortable to them.

Debit Card/ATM Processing

Debit card/ATM processing is almost like accepting credit cards except for the fact that your customers are using their debit card to complete an order. Funds are deducted from the customers checking account for purchases.

IVR Terminals

Interactive Voice Response Terminals, also referred to simply as IVR, are a relatively new method of being able to process credit cards, check cards (debit cards with Visa or MasterCard logo on them), and checks (ACH – Automatic Check Handling) via any touch-tone telephone.

PayPal

Over 8 million registered users use PayPal as their means for payment of online products and services. PayPal makes a great addition to your array of payment acceptance methods.


e-Checks & Checks by Phone/Fax/E-mail

e-Checks or Checks by phone/fax/e-mail are a good additional payment solution to credit card acceptance which allows you to collect payment via check over the phone, by fax, and even off your order form on your web site.

Micropayments (e-Wallet)

Micropayments are used to process small transaction amounts (from a few cents to $10 USD) that would otherwise severely limit your amount of profit if processed the same as credit cards.

Digital Cash (e-Cash)

Digital Cash is basically an encrypted serial number (online e-currency) that simply represents money. The customer then can spend the money at different merchants that support the Digital Cash provider the customer signed up with. Digital Cash gives added security and peace of mind to customers as they are not actually using their credit card directly to make purchases.

Escrow Services

Interested in added security of high dollar purchases and auction transactions? Then Escrow services are for you. They ensure the seller gets paid and the buyer is happy with their purchase.


Check Guarantee/Check Verification

Check guarantee is a program in which you are guaranteed to be paid on your checks. There’s no need to worry about accepting checks or collection on returned checks. Usually, the cost for this solution is about the same as credit card acceptance, however, some may offer it for a lower price. Check with your Merchant Account Provider for further details.

Electronic Funds Transfer (EFT)

EFT is a method for transferring money automatically by using the facilities of the Automated Clearing House, an entity associated with the Federal Reserve Banks. EFT is the only system by which a merchant can initiate a transaction to collect money from the bank account of a customer located anywhere in the USA. In addition, it can be used to transfer money outwardly to pay bills.

Automated Clearing House (ACH) & ACH Services

It is most often used to process low-dollar repetitive retail payments. Financial Institutions that are members of the FED ACH System send batches of credits and/or debits into the system, and the system sorts the items from all batches submitted, and routes them to the appropriate receiving financial institution. The system is used primarily for pre-authorized recurring payments such as payroll, corporate payments to vendors, Social Security payments, insurance premium payments and utility payments. Section also covers ACH Services like Electronic Check Conversion (ECC), Accounts Receivable Truncated Checks (ARTC/Lockbox), and Returned Check Collections (RCK).


Electronic Benefits Transfer (EBT)

Grocery shopping is one of the most widely performed activities around the world. If you are food merchant, you probably know that not everyone pays for their food with cash or credit cards, but many use food stamps as well. Now that paper is becoming a less and less common form of the food stamp. Many purchases are made with the use of a single card called Electronic Benefits Transfer card.

 GOOD NEWS

Are you tire to find a professional payment gateway for your great business ?
we are the professional online payment gateway ,we can accept visa,master ,JCB,AE credit card payment method ,all high risk  business types welcomed! 99.9 % approval rating!Never locked your merchant account!Low, competitive rates .

skype:goodluck3801
E-mail: paymentgateway@yahoo.cn
website site:http://www.ecpss.com/index_en.html    

New Payment Solutions

What will this 21st century bring to the world of payment acceptance? Use this page to keep up to date on the latest trends and happenings in new and updated ways to accept payment from customers. As the Internet grows, more automatic and less effort driven solutions will be developed to aid shoppers.

Smart Card Processing

Credit cards with a “brain”
Smart cards and credit cards are basically the same except for the fact smart cards contain a smart chip inside them that secures personal information about the cardholder making for easier and more secure purchases both in the retail and Internet industries.


IVR Terminals

Reduce chargebacks and fraudulent orders using any touch-tone phone
IVR Terminals, also referred to as Interactive Voice Response Terminals are a relatively new method of being able to process credit cards, check cards (debit cards with Visa or MasterCard logo on them), and checks (ACH – Automatic Check Handling) via any touch-tone or wireless cell phone. IVR Terminals help to greatly reduce chargebacks and fraudulent orders.


GOOD NEWS

Are you tire to find a professional payment gateway for your great business ?
we are the professional online payment gateway ,we can accept visa,master ,JCB,AE credit card payment method ,all high risk  business types welcomed! 99.9 % approval rating!Never locked your merchant account!Low, competitive rates .

skype:goodluck3801
E-mail: paymentgateway@yahoo.cn
website site:http://www.ecpss.com/index_en.html     

Tuesday, February 14, 2012

Greater Security, Flexibility, and Global Acceptance Driving EMV Adoption in U.S.

On August 9, 2011 Visa moved forward with a three-part plan to speed up the adoption of EMV chip technology in the United States. Globally, for both credit and debit cards, the standard represented 40.1 percent of the payment cards in circulation for the first quarter of 2011 with 71 percent of the POS devices in the world capable of using the cards. The U.S., however, has dragged its heels on embracing EMV cards, with companies issuing them to their customers who travel abroad and not pushing acceptance of the more secure standard for domestic transactions.

EMV Offers Strong Anti-Fraud Protection

When compared to traditional magnetic strip cards, an EMV card is much harder for thieves to manipulate for purposes of fraud. The authentication and verification of the associated PIN is automatically performed by the chip, with each transaction carrying a unique data “stamp.” This dynamic feature makes the card’s data relative to the given transaction only, and both symmetric and asymmetric cryptography are used. The entire system of key management is elaborate and secure to create integrity in the transaction.
There are no numbers on fraud with these cards in the U.S. for obvious reasons, but statistics gathered by groups like Banque de France, UK Payments Administration, and Interac in Canada prove that EMV technology lowers fraud at physical points of sale, at automated teller machines, from counterfeiting activities, and in scenarios where the card is not present.

Failure to Implement EMV is a Problem for U.S. Travelers

Another factor driving acceptance of the technology in the U.S., beyond the fact that EMV is a sophisticated and secure platform, is the fact that EMV has emerged as a global standard. American business travelers are not only inconvenienced, but are at a disadvantage when they travel abroad and attempt to use archaic magnetic strip cards that are refused at POS transactions and at unattended terminals. Additionally, in accepting EMV, merchants are positioning themselves to take contactless and mobile payments as well, like those enabled by near field communications on smartphones.

EMV Also Driving Mobile and Contactless Transactions


At the POS, a mobile payment transaction is not seen as any different than a card transaction since the payment is based on the EMV specifications. Although there are few contactless terminals in the U.S. at present — maybe 7 million locations representing 2 percent of merchants –more than 50 percent of Americans have smartphones. Their perception of what they can do with those units rather than just make phone calls is expanding daily, and they are rapidly becoming accustomed to the convenience of having a hand-held computer at their disposal.

Visa’s plans to accelerate the acceptance of EMV payment technology in the U.S. are well timed, and geared toward a market already ripe for the more secure transaction, with some banks and currency exchange companies already issuing EMV cards. Perhaps most significantly, Walmart is in the process of upgrading its POS devices for EMV compliance. The widespread adoption of the more secure EMV platform will depend both on consumer demand and attractive incentives like those being offered by Visa to merchants to make the change.
The EMV picture should look far different in the U.S. by the end of 2012, when the country should be closer to accepting that EMV cards are the global standard and that American consumers are being left wide open to fraud with the out-of-date metal strip technology.

GOOD NEWS

Are you tire to find a professional payment gateway for your great business ?
we are the professional online payment gateway ,we can accept visa,master ,JCB,AE credit card payment method ,all high risk  business types welcomed! 99.9 % approval rating!Never locked your merchant account!Low, competitive rates .

skype:goodluck3801
E-mail: paymentgateway@yahoo.cn
website site:http://www.ecpss.com/index_en.html    


Offshore High risk Merchant Account

If your business one of the following: retail, online pharmacy, travel, ticketing, entertainment, etc. please complete the form below to receive a rate quote within 48 hours or less. Our featured providers are specialized in offering payment solutions to both low and high risk merchants.

  • The most competitive offshore processing costs that you’ll find anywhere.
  • Accept major credit cards, debit cards and checks.
  • Back-end reporting, query, and data download tools
  • Multi-currency processing and settlement
  • Technical support
  • Simple integration
  • Recurring billing
  • Advanced fraud prevention solution
  • 3D Secure is supported
  •  

Offshore Merchant Account Inquiry/Pre-Application


Simply complete the form below and a sales representative will contact you shortly with more information and your rate quote.
Are you tire to find a professional payment gateway for your great business ?
we are the professional online payment gateway ,we can accept visa,master ,JCB,AE credit card payment method ,all high risk  business types welcomed! 99.9 % approval rating!Never locked your merchant account!Low, competitive rates .

skype:goodluck3801
E-mail: paymentgateway@yahoo.cn
website site:http://www.ecpss.com/index_en.html   

How to reduce chargeback and fraud efficiently

Merchant concern about online credit card fraud and chargebacks is rising at a significant rate. According to the 2001 Online Fraud Report, conducted by Mindwave Research, it revealed that, “41% of merchants say the issue of online credit card fraud is ‘very serious’ to their business.” As e-commerce continues to flourish the number of instances of credit card fraud and chargebacks will continue to mount higher. It should go without saying that the need to take certain measures to reduce and virtually eliminate chargebacks and fraud is certainly paramount.
Chargeback, the word that Internet merchants fear. A chargeback is what it’s called when a transaction is reversed. In other words, rather than adding money to your account it is deducted. Chargebacks can occur for a wide variety of reasons, such as double-charging, credit card expiration, bank error and customer disputes. If you get too many chargebacks against you, there is a possibility that you will lose your merchant account. Once you’ve lost your merchant account you are placed on the Visa/MasterCard Terminated Merchant File (TMF/MATCH list) for several years which all Merchant Account Providers have access to, and if they find you on the list they won’t reissue a merchant account to you. If you are one of those merchants who have lost their merchant account, there is still hope. Bank Card Law specializes in helping companies who’ve lost their merchant account because of excessive chargebacks.
Here are some ways you can greatly reduce the instances of chargebacks and fraud, even potentially eliminate the risk altogether:


#10 If the customer is present examine the card carefully
One common sense method to fight chargebacks is to examine the customer’s card. Look at the expiration date and the signature panel for good measure. If the card does not have a signature you are free to check the customer’s ID. You may also request that the customer signs the card and if the customer refuses, you may decline to accept the customer’s credit card.
#9 Verify CVC2 and CVV2 Verification Numbers
This tactic alone can not only reduce instances of chargebacks by 26%, according to Visa, but also reduce any pass-through fees that may be charged when a credit card order is conducted. On the back of MasterCard, most Visa and Discover credit cards is a 3-digit security code located right after your credit card number. Requiring customers to give the 3-digit code acts as an additional verification measure. American Express cards also have a similar security code that is located on the front of the card right above the cardholder’s account number and is usually 4-digits long. Most online payment processors support entering the security codes when processing credit card orders. Check with your payment gateway provider (i.e. Verisign, Authorize.Net, ECHO Inc., etc) for details.

#8 Use Address Verification System (AVS)
AVS checks to ensure the address entered on the order form matches the address to where the cardholder’s billing statements are mailed to. People ordering products and/or services using a stolen card number will never use the real cardholder’s billing address, so this is your chance to stop the order before it’s too late. AVS only works with orders conducted in the US. Failure to use AVS when processing credit card transactions will always result in paying higher credit card processing fees.
#7 Scrutinize orders from developing foreign countries
A large percentage of fraudulent Internet purchases are made from Indonesia, Russia, and other eastern block or developing countries. Accept orders from such countries at your own risk until a worldwide AVS system is developed.
#6 Let customers know what name will appear on statements
Many merchants who use 3rd Party Processing companies have run into problems because the company name that appears on cardholder’s monthly statements is usually the name of the 3rd party processing company and not the company name of the site the cardholder made their purchase from. This isn’t always the case, but in many cases it is. If you use a 3rd party processor, and even if you don’t, make sure the customer knows what name will appear on their credit card statement at the end of the month. This will help to reduce any confusion that might would otherwise occur.
#5 Handle suspicious orders accordingly
If an order seems suspicious the best way to handle the situation is to either call or e-mail the customer and attempt to verify that they placed the order. As a rule of thumb, if in doubt, check things out. It may be a good idea that if a customer makes an unusually large volume purchase from your site to follow-up with a verification call. This is where a system like VoiceStamps, featured here, can come in very handy.
#4 Watch out for orders using free e-mail addresses
Be wary of accepting orders from people who used a free e-mail address when ordering (i.e. Hotmail, Yahoo, etc.). Tracking people who used a free e-mail address is almost impossible, it’s much easier for them to get away then if they used their Internet Service Provider (ISP) or their own company web site e-mail address. To check whether an e-mail address is a freebie or not just take the part of the address after the “@” symbol, add “www” to the front of it and see what website it brings up (i.e. joe@yahoo.com = www.yahoo.com).

#3 Signatures on delivery
If your business delivers products use a carrier that requires a signature on delivery, and allows you to have a copy of the signature. Retain these for your records.
#2 Request fax copies of ID and credit card
You may want to request your customer to fax a copy of both sides of their credit card and driver’s license. This tactic usually works best in a B-to-B (business to business) sales environment. While this is not a defense under Visa or MasterCard rules, it is yet another way to deter fraud.
#1 Posting a warning message
Taking the time to post a warning message on your order page to those who may attempt to make a fraudulent order will greatly deter the number of instances of fraud. Be sure to mention that IP (Internet Protocol) addresses are being logged. IP addresses can come in handy when locating people about fraudulent orders.
Taking measures to deter and eliminate fraud and chargebacks from occurring are a necessity in order to operate a successful online business. Each day companies dedicated to risk management are developing solutions to provide merchants, like yourself, with extra protection because of the financial burdens chargebacks and fraud can bestow if ignored.
Are you tire to find a professional payment gateway for your great business ?
we are the professional online payment gateway ,we can accept visa,master ,JCB,AE credit card payment method ,all high risk  business types welcomed! 99.9 % approval rating!Never locked your merchant account!Low, competitive rates .
skype:goodluck3801
E-mail: paymentgateway@yahoo.cn

Monday, February 13, 2012

Online Payment and Credit Card Processing Options


By offering a credit card processing and online payment service such as Paypal or Worldpay on your website, you enable your visitors to make direct payments into your merchant account. Many online payment services are highly secure, free and offer cheap credit card processing services. Most online payment providers collect a small commission for the credit card processing service.
ECPSS
Ecpss is a leading e-payment service provider , with a mission to provide better e-payment solutions and value-added financial services through technology and innovation.. Ecpss is the rising leader in secure online payment solutions that was founded to facilitate safe instant payments between individuals and online businesses.
Under the "Ecpss" brand, the Company's products and services aspire to support a safe and convenient transaction environment and establish secure, fast and confidential payment platform for e-commerce operators, Internet content providers and individual users.. "Ecpss" is the number one choice for making money and sending payment online.

The Company has established strategic partnerships with VISA, MASTERCARD, JCB, AE.
Ecpss has members in 190 + countries, supports 21 currencies and offers localized banking in 46 countries. We are always working on making our services available to more people all over the world.we can accept visa,master ,JCB,AE credit card payment method ,all high risk  business types welcomed! 99.9 % approval rating!

PayPal


Paypal is the easiest way for customers to make online payments. Payment is made either directly through your website or via e-mail. Paypal charges a small fee for credit card processing. When a visitor from your website initiates to pay you using Paypals online payment service, the customer is sent to a secure Paypal website. He or she than enters the details of their credit card for verification and processing. After the transaction, Paypal will redirect the user back to your website.
WorldPay


WorldPay is a popular online payment service used by many ESL tutoring services, or with companies dealing with foreign currency. Worldpay offers a very flexible and simple solution to multi-currency payment. In addition to visitors making online payments on your website, Worldpay allows you to collect payments by phone, fax or mail using the same online payment processing service.
To use the services of Paypal, Worldpay or some other online payment and credit card processing service provider, you will have to copy and paste some simple HTML codes into your web pages.
skype:goodluck3801
E-mail: paymentgateway@yahoo.cn

Wednesday, February 8, 2012

Choose Your Payment Gateway in Easy Steps

 1  Know Payment Gateway Definition
Payment gateway is an infrastructure to enable a web merchant having an online ECommerce store to charge a customer from his credit/debit/prepaid card or bank account(netbanking) resulting in transfer of funds electronically from customer’s account to merchant’s account.
 2  Learn payment gateway & Ecommerce terminology

Payment Gateway
A payment gateway is an Ecommerce online transaction processing platform/interface which allows a merchant(you) to receive payment online from customers using various types of cards and netbanking facilities
 
3  Read Pros & Cons of accepting cards online?
4  Are you selling any banned products?
5  Which factors to look for when comparing payment gateways?
6 Learn about Merchant Account Fees that you may need to pay to payment gateway service providers
7 Do a Price Comparison of payment gateways in China.
 
8 Any doubts? Raise it in our Payment Gateway Forum. We'll try to respond to your queries in the discussion forum. 9 Go through this checklist before you apply for a merchant account so that your website does not get rejected! 10 Done. You'd have finalized a suitable payment gateway. Apply for it.
 We are professional High risk products of online payment gateway leader , we have established strategic partnerships with VISA, MASTERCARD, JCB, AE. we have members in 190 + countries, supports 21 currencies and offers localized banking in 46 countries. We are always working on making our services available to more people all over the world.

we are the professional online payment gateway ,we can accept visa,master ,JCB,AE credit card payment method ,all high risk  business types welcomed! 99.9 % approval rating!
24/7/365 customer service   
All high risk business types welcomed!
99.9 % approval rating!
Never locked your merchant account!
Low, competitive rates
Contact info : skype name:goodluck3801
E-mail: paymentgateway@yahoo.cn
website site:http://www.ecpss.com/index_en.html 

Monday, January 9, 2012

What are the specific costs of an online payment gateway?

Discount Rate
The first thing you need to know about is discount rates. These rates (usually 2-6%) are commissions split by a few parties taken from your client’s payment. They are attributed to your merchant account provider and/or payment gateway and finally, the credit card provider. They will vary greatly depending on the payment gateway/ merchant account setup you choose but will be involved in any credit card transaction you ever make.

With some payment gateways, the discount rate will decrease as the your total monthly sales amount is increased through that gateway. For example, with Google Checkout, the discount rate a totally monthly sales of less than $3000 will be 2.9% but for over $10,000, it would decrease to 2.2%.
Monthly Fees
Almost all payment gateways that require a merchant account charge a monthly fee. The more services and functions your gateway offers  (or you choose), the higher these fees will be.

It’s worth noting that some of these fees are optional, and if you integrate with an application to handle your e-commerce, you may not need some options. For example, some payment gateways will add an extra charge if you want to use their service to enable auto-billing (the ability to process regular, pre-authorized payments on a client’s credit card).  If you set up auto-billing in ECPSS merchant account , you don’t need to pay anything extra to your payment gateway.
One common value-added feature you might want to consider is a fraud detection toolbox. With most payment gateways, you are given a number of tools to help you guard against fraud, such as filters to define the scope of people or places you receive payments from. As an example, ECPSS payment offers their Advanced Fraud Detection Suite. It’s a good idea to add this service if you will be accepting payments from people who you do not have an existing relationship with (ie people who sign up on your website, as opposed having been a client for 10 years) because it will help reduce chargebacks.
Per Transaction Fees
Lastly, for each transaction you process, most payment gateways charge a flat fee. It’s usually under fifty cents per transaction, but I’m afraid this fee is pretty much unavoidable.
Setup Fee
When you sign up for a payment gateway, there is also usually a setup fee. Sometimes, it’s free (like PayPal Standard), but most of the time the setup fee ranges from $49 – $250. The good news = at least the setup fee is only a one-time charge, and I am positive you will quickly earn it back.

   Laid out like this all in one list, the costs may seem surprising. But when you factor the costs into enhanced convenience for your customers and dramatically improved cashflow, as well as the time your will save collecting from your customers (no checks in the mail, or records to update because ECPSS payment gateway will do that automatically), it is well worth it.

How do payment gateways work?

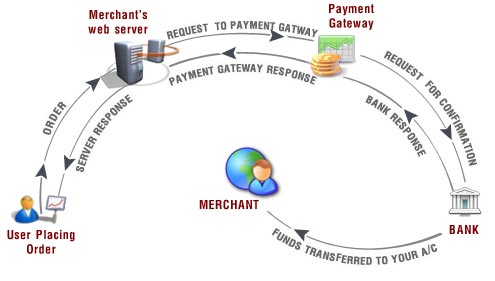
        You know those machines where you swipe your credit card in restaurants and retail stores? A payment gateway is kind of like one of those, just without the need for a card to be present to be charged. It is literally a gateway between you, your client, your client’s credit card provider and your bank.
The main job of the gateway is to validate your client’s credit card securely, make sure the funds are available, and get you paid.
How Payment Gateways Work
   Some gateways also require what’s called a merchant account. A merchant account is essentially just a special kind of bank account that handles your funds received via credit cards. If you have a storefront or a retail business, and are swiping people’s cards, then you already have a merchant account.
Even if you do already have a merchant account, there’s still one step you should take if you want to start accepting online transactions. You’ll need to give your bank a call and ask them to set you up for an Internet merchant account. This is different from a regular merchant account, because it gives you the ability to process credit cards without the card being physically present for the transaction.

If you do not have a merchant account or are not interested in getting one (it can take some jumping through hoops to get set up), ECPSS can be a great way to start. ECPSS functions a little like a merchant account add-on for your existing bank account. You can collect credit card payments in your ECPSS account, then link it to a personal bank account (most people forget this step) to transfer the funds as necessary (note: not automatically – you have to specifically choose to transfer the funds).

   If you would like to get a merchant account (a good idea if you’re processing a lot of transactions), then all the payment gateways will help you get one. The process does require some paperwork, however, and a few days (two to five) for them to run the appropriate credit checks.

Wednesday, December 28, 2011

credit card processor advantage


While it may be tempting to try to get, and manage, your own merchant account, there are several advantages to choosing ECPSS.
  • Money & resource savings – ECPSS completely automates the sales processing functions for your website, eliminating your monthly overhead and reducing all of your costs into one set rate per transaction.
  • Implementation process – ECPSS allows you to get your site up and running quickly and easily. No scripting or complex programming is necessary and there is no equipment or software to buy.
  • Reputation and confidence – Processing transactions since 1998, ECPSS consistently maintains the highest service standards in the industry, producing strong consumer confidence for our service and your website.
  • Consumer support - Low processing rates are meaningless without good, 24/7/365 end-user and consumer support. ECPSS's live billing support center means you don't have to house and staff your own consumer support team, and ECPSS also offers an online service center for quick order lookups, cancellations and tracking.
  • Allocation of resources - With ECPSS managing the payment processing functions for the sale of your goods, you are free to allocate more resources to more important business tasks, such as sales forecasting, marketing, order fulfillment and membership services.
  • Fraud detection – ECPSS maintains a proprietary and advanced fraud detection system, built to identify and reduce online fraud. You can take advantage of ECPSS's expertise to minimize fraudulent transactions and build increased consumer confidence.
  • Scalability – ECPSS is scalable, allowing you to expand or shrink your e-commerce capabilities in accordance with your business requirements. With no monthly minimum, you pay a set fee that is based on your sales volume.

The advanced Online Payment Processors


                                                        Set up, manage, configure
                     Selecting the right online payment processor has a huge impact on your business. It has to be robust enough to process all of your sales, while remaining customizable and user-friendly enough to meet your specific operational and administrative needs. ECPSS payment processing certainly has all the features you need to be successful, and a multitude of tools to help drive results.

               Integration Center – a user-friendly online interface full of helpful tips, tools and resources regarding account set-up, ECPSS services and features, customizable settings within the Admin Portal, and more.

               APIs – ECPSS APIs and Subscription Management System (SMS) enable you to have high degrees of account management directly from your website or control panel.
App Portal – for years developers and programmers have been creating applications to complement ECPSS systems and enhance some functionalities. The App Portal is a centralized online location for these created products and toolsets where you can view and select any you wish to use, or upload your own complementary application.

                  However you want to set up or configure your account, ECPSS has the resources to help. Should you require additional assistance, several FAQs, Demos, and the online Knowledge Base are available as well, and the Support Team is ready to assist 24/7/365.